Beyond the Credential: Building a Wealth Advisory Team That Matches the Complexity of Your Finances
There is a particular frustration familiar to many high-net-worth Americans: the sense that one's financial advisor, despite impressive qualifications and genuine competence, is simply operating at the wrong altitude. The conversation keeps returning to asset allocation percentages and retirement projections. Questions about private fund structures, tax-loss harvesting across a multi-entity family office, or the coordination of an irrevocable trust with a charitable giving strategy are met with vague reassurances or referrals to yet another specialist who does not quite speak the same language.
This is not a failure of individual advisors. It is a structural mismatch — one that becomes increasingly costly as the complexity of a client's financial life grows. And for investors managing substantial, multi-dimensional wealth, the cost of that mismatch is not merely inconvenience. It is measurable, compounding opportunity loss.
Diagnosing the Mismatch
The advisory industry in the United States is vast and varied. It encompasses everything from fee-based fiduciaries managing modest retirement accounts to multi-family office teams overseeing nine-figure legacies. The credentials that populate an advisor's business card — CFP, CFA, ChFC — signal a baseline of competence, but they do not reliably indicate depth of experience with the specific challenges that accompany significant wealth.
High-net-worth clients often arrive at the recognition of a mismatch gradually. Perhaps their advisor recommended a straightforward portfolio rebalancing without flagging the embedded tax liability. Perhaps a conversation about private equity access was deflected with a comment about liquidity risk — a legitimate concern, but one that sidestepped the deeper question of whether the advisor even had access to institutional-quality private market opportunities. Perhaps estate planning discussions never progressed beyond the basics of a revocable living trust.
The warning signs are worth naming explicitly:
- Reactive rather than proactive communication. An advisor who reaches out primarily in response to market volatility, rather than initiating strategic conversations, is likely managing breadth rather than depth.
- Limited alternative investment access. If the universe of available investments consists primarily of mutual funds, ETFs, and publicly traded securities, the advisor's platform may not be structured for sophisticated wealth management.
- Siloed thinking. Wealth at scale requires the coordination of investment management, tax planning, estate strategy, insurance, and philanthropy. An advisor who operates in isolation from these disciplines is providing an incomplete service.
- Generalist language around specialist topics. Vague or hedged responses to direct questions about specific strategies — qualified opportunity zone investments, grantor retained annuity trusts, direct indexing — suggest a knowledge gap that matters.
The Case for a Specialized Wealth Team
The most effective response to advisory complexity is rarely to find a single, more capable individual. It is to build — or gain access to — a coordinated team of specialists whose collective expertise spans the full landscape of high-net-worth financial management.
The multi-family office model, once accessible only to the ultra-wealthy, has become considerably more attainable in recent years. A growing number of registered investment advisors and independent wealth management firms now offer team-based service structures that integrate investment management with tax counsel, estate planning, and family governance. For investors who have not yet crossed the threshold where a single-family office is warranted, these platforms represent a meaningful upgrade in advisory sophistication.
When evaluating whether a team-based model is appropriate, the relevant question is not simply the size of one's investable assets. It is the complexity of one's financial situation. A business owner navigating a liquidity event, a family managing assets across multiple trusts and entities, or an investor with significant exposure to alternative asset classes may benefit from coordinated advisory services well before reaching the traditional family office threshold.
A Framework for Evaluating Advisory Expertise
Selecting or reassessing an advisory relationship requires a structured approach. The following framework offers a practical starting point.
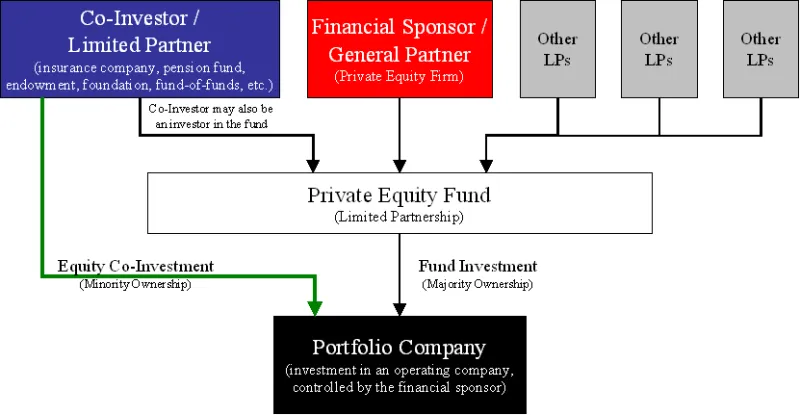
Assess depth of alternative investment experience. Ask directly: What percentage of your current client assets are allocated to private equity, private credit, or real assets? Through which platforms or fund managers do you access these opportunities? The answers will quickly reveal whether the advisor has genuine fluency in this space or is offering token exposure through a single feeder fund.
Evaluate tax integration. A high-quality wealth advisor should be able to articulate, in specific terms, how their investment recommendations interact with your tax situation. Ask for examples of tax-aware strategies they have implemented for clients with comparable profiles. If the response is generic, the integration may not be as robust as advertised.
Probe estate and generational planning capabilities. Questions about dynasty trust structures, generation-skipping transfer tax strategies, or the coordination of charitable vehicles with estate plans will quickly distinguish advisors with genuine estate planning depth from those who rely on referrals to outside counsel without meaningful coordination.
Examine the compensation structure with precision. Conflicts of interest in financial advice are not always obvious. Fee-only fiduciaries eliminate commission-based incentives, but even within the fee-only model, asset-based fees can create subtle biases toward keeping assets under management rather than directing capital toward strategies — such as paying down business debt or funding a private deal directly — that might better serve the client's overall financial position.
Request a comprehensive financial review. Before committing to or continuing a relationship, ask the advisor to conduct a holistic review of your financial situation, including tax returns, estate documents, insurance policies, and existing investment accounts. Their ability to synthesize this information and identify strategic opportunities — or inefficiencies — is perhaps the clearest indicator of their actual capability.
Restructuring an Existing Relationship
For investors who have worked with an advisor for years, the prospect of reassessment can feel disloyal or disruptive. But the fiduciary standard that governs the best advisory relationships runs in both directions: just as advisors are obligated to act in clients' best interests, clients are obligated to themselves to ensure those interests are actually being served.
A candid conversation with an existing advisor — one that clearly articulates the need for greater sophistication, broader access, or more integrated planning — is often a productive first step. Many advisors will welcome the opportunity to expand the scope of the relationship or will honestly acknowledge the limits of their platform and facilitate a transition to a more appropriate provider.
The goal is not to find an advisor who is impressive on paper. It is to find — and retain — professionals whose capabilities genuinely match the complexity of your financial life, and who have the intellectual honesty to acknowledge when they do not. At the level of wealth where the decisions truly matter, that distinction is everything.