Votes as Leverage: How Affluent Investors Are Quietly Rewriting Corporate Governance From the Inside
For most of American financial history, the individual investor's relationship with corporate governance amounted to little more than a rubber stamp. Proxy ballots arrived in the mail, were skimmed or ignored, and the machinery of shareholder democracy churned forward without meaningful participation from the people who actually owned the companies. That dynamic is shifting—quietly, methodically, and with considerable consequence for those paying attention.
A growing segment of affluent investors, particularly those with concentrated equity positions in the seven-figure range and above, are discovering that their ownership stakes carry far more operational weight than quarterly dividends and capital appreciation. Through strategic proxy voting, coalition formation, and targeted engagement with corporate boards, these investors are influencing executive compensation structures, capital allocation decisions, and long-term strategic direction—all without liquidating a single share.
The Mechanics of Shareholder Influence
Proxy voting is, at its core, the exercise of ownership rights. Every share of common stock in a publicly traded US company carries with it the right to vote on matters ranging from director elections to executive pay packages to proposed mergers. For most retail investors, these rights go largely unexercised. For the sophisticated investor who understands how to deploy them, they represent a legitimate form of corporate leverage.
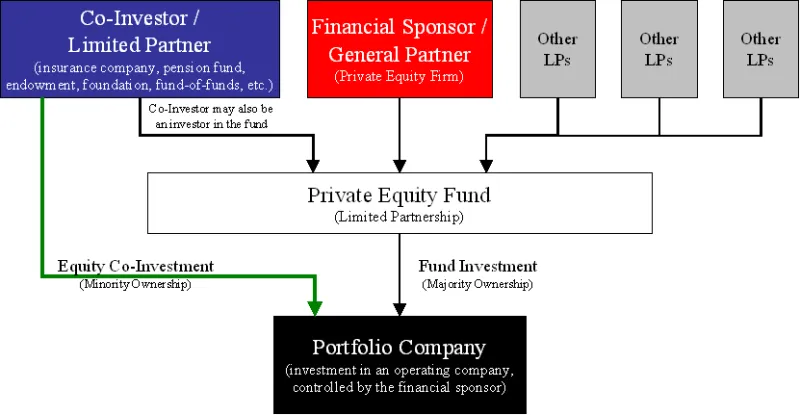
The pathway to meaningful influence typically begins with one of three approaches. The first is direct engagement—reaching out to investor relations departments or board members to communicate concerns or proposals ahead of annual meetings. The second involves filing or co-filing shareholder resolutions, which, if they meet the SEC's threshold requirements, must be included in the company's official proxy materials and put to a vote of the full shareholder base. The third, and most powerful, is coalition building: aggregating voting power across multiple like-minded investors to achieve the kind of bloc influence that boards cannot easily dismiss.
None of these mechanisms require the resources of a Carl Icahn or a Bill Ackman. What they require is patience, preparation, and an understanding of how corporate governance actually functions.
When Individual Stakes Become Collective Power
The mathematics of shareholder democracy reward coordination. A single investor holding 0.4% of a company's outstanding shares wields modest influence in isolation. Five such investors, aligned on a specific governance objective and voting in concert, represent a 2% bloc—enough to attract board attention and, in contested situations, potentially tip the outcome of director elections or shareholder resolutions.
Organizations such as the Council of Institutional Investors and various ESG-focused shareholder advocacy groups have long facilitated this kind of coordination at the institutional level. More recently, platforms designed for individual accredited investors have begun offering similar coalition infrastructure, allowing high-net-worth individuals to identify fellow shareholders with shared objectives and coordinate voting strategies without running afoul of SEC proxy solicitation rules.
The results of this coordinated approach have been materially significant in documented cases. At several mid-cap US companies over the past decade, organized minority shareholder coalitions have succeeded in replacing underperforming board members, unwinding ill-considered acquisitions, and forcing the adoption of more transparent executive compensation frameworks—outcomes that subsequently contributed to measurable share price appreciation.
The Financial Case for Active Ownership
Skeptics sometimes frame shareholder activism as a values exercise rather than a financial one—the province of socially conscious investors willing to accept suboptimal returns in exchange for ideological satisfaction. The evidence does not fully support this characterization.
Academic research, including studies published by Harvard Law School's Program on Corporate Governance, has consistently found that targeted activist campaigns generate statistically significant abnormal returns in the period surrounding their public disclosure. More relevant to the long-term holder, however, is the evidence suggesting that improvements in corporate governance metrics—board independence, executive pay alignment with performance, capital return discipline—correlate meaningfully with sustained shareholder value creation over multi-year horizons.
For the affluent investor who holds a significant position in a company and has no intention of selling, the calculus is straightforward: if governance dysfunction is suppressing the value of an otherwise sound business, engaging the machinery of shareholder democracy is not an ideological act. It is a rational exercise of ownership rights in service of financial outcomes.
Navigating the Regulatory Landscape
Engaging in proxy-related activity requires careful attention to SEC regulations, particularly those governing proxy solicitation and the disclosure of coordinated voting arrangements. Investors who solicit the votes of more than ten other shareholders on a proxy matter are generally required to file soliciting materials with the SEC under Schedule 14A rules. Shareholders who cross the 5% ownership threshold in a public company must file a Schedule 13D or 13G, depending on the nature of their intentions.
These are not prohibitive barriers, but they are meaningful ones. High-net-worth investors who wish to engage in coordinated activism should work closely with securities counsel experienced in proxy regulation before initiating any formal coalition effort. The regulatory framework exists to protect all shareholders, and navigating it properly is both a legal obligation and a strategic asset—investor credibility in the governance arena depends heavily on procedural correctness.
Values Alignment as a Byproduct, Not a Prerequisite
One of the more interesting developments in the shareholder engagement space is the degree to which financial and values-based objectives have converged for many affluent investors. A portfolio holder who believes a company's board lacks adequate independence is not necessarily making an ethical argument—they are identifying a structural risk factor that academic research associates with weaker long-term performance. An investor who pushes for clearer disclosure of environmental liabilities is, in many cases, simply demanding that material risks be priced into the market's understanding of the business.
This convergence means that the dichotomy between financial activism and values-driven engagement is less sharp than it once appeared. For the discerning investor, proxy strategy can simultaneously serve the goal of maximizing risk-adjusted returns and the goal of ensuring that the companies they own conduct themselves in ways consistent with their broader principles.
Positioning Proxy Strategy Within a Broader Wealth Framework
Shareholder engagement is not a standalone investment thesis. It is most effective when integrated into a broader ownership philosophy—one that treats equity stakes not as abstract financial instruments but as genuine fractional ownership of operating businesses. Investors who adopt this perspective naturally take a more active interest in governance, management quality, and long-term capital allocation.
For those managing substantial concentrated positions, proxy strategy also offers a meaningful alternative to the binary choice between holding and selling. Rather than exiting a position because of governance concerns—potentially triggering significant capital gains—the engaged investor can work to address those concerns directly, preserving the economic exposure while attempting to improve the underlying quality of the business.
In this sense, the proxy ballot is not merely a procedural formality. For the affluent investor who understands its potential, it is one of the more underutilized tools in the wealth management arsenal—a mechanism for exerting real influence over corporate America, one vote at a time.